Most people are taught to think about credit in one of two ways: as a trap to avoid, or as a last resort for the day cash runs out. Both views are understandable. Anyone who has watched interest pile up, or felt one missed payment turn into months of stress, has good reason to be wary. But the wariness hides something important, and it costs people options every year.
Credit is not only about borrowing money. Handled well, it is about access, timing, flexibility, and negotiating power. Reframing credit as a resource means seeing it the way financially steady people quietly do: not as extra income and never as free money, but as a tool that, kept in good condition, makes almost every other money decision cheaper and easier.
This guide explains the mindset in full: what credit actually gives you, how lenders judge it, the rules that keep it working for you instead of against you, how to use it strategically for growth, and how to rebuild it if it currently feels like a burden.
What It Means to Treat Credit as a Resource
A resource is something you maintain because it is useful when the moment comes. A savings account works that way, and so does a good professional reputation. Credit belongs in the same category. Its value is not the balance you could run up today; it is the doors that stay open because lenders, landlords, insurers, and sometimes employers see a record of someone who keeps commitments.
That shift in framing changes behaviour. If credit is a trap, the only question is how to escape it, and the answer is usually to avoid it entirely, which quietly makes mortgages, car finance, and even renting harder and more expensive later. If credit is a resource, the question becomes more useful: how do I build it, protect it, and use it deliberately, at the lowest cost, for things that genuinely improve my position?
Notice what the resource view does not say. It does not say debt is good. It does not say a higher limit is an achievement worth celebrating with spending. It says that in a financial system that runs on records and scores, the person with a strong, well-kept credit profile simply has more and cheaper choices than the person without one — and that those choices are worth managing on purpose.
Why Most People Only See the Trap
The fear has real roots. Credit is usually introduced to people at their most vulnerable: a first card with a tempting limit and a confusing statement, a loan sold at the till, an emergency that forces borrowing at the worst possible rate. Marketing encourages spending; almost nothing teaches maintenance. So the lived experience of credit, for many households, is interest charges and minimum payments, and the lesson they draw is that credit itself is the problem.
There is also a timing problem. The benefits of good credit are invisible and arrive years later, disguised as things that did not happen: the mortgage that was approved without drama, the deposit that was not demanded, the rate that was a little lower than a neighbour’s. The costs of bad credit are equally invisible, buried in higher prices paid quietly over years. Because neither side sends you a bill labelled “your credit mindset,” most people never see the full picture.
Seeing it is the reframe. Credit is a system with rules, and like any system it rewards the people who learn the rules early.
| 🔗 You may also like: |
|---|
| Credit counseling and debt management guide |
| 7 Proven Ways the Right Accounting Platform Can Make Bookkeeping Easier |
The Real Value of Credit Is Options
The most useful thing good credit gives you is not purchasing power. It is optionality: having more than one workable move when something important happens. The car that gets you to work needs repairs this week, not next month. A landlord is choosing between two applicants. A cheaper loan could replace three expensive ones. In each case, strong credit widens the path.
Think of healthy credit as a reserve that sits quietly in the background. When borrowing costs rise across the market, a stronger profile still tends to qualify for the better end of the offers. When an opportunity appears — a career move, a relocation, a chance to consolidate expensive balances into one manageable payment — credit smooths the transition. When cash flow is disrupted, access to reasonably priced credit buys breathing room while you protect savings and income, instead of forcing desperate decisions at the worst moment.
The reverse is also true, and it is why careless use is so costly. Misused credit does not only create balances; it shrinks future choices. A maxed-out card, a missed payment, a limit cut by a nervous lender — each one quietly converts a flexible resource into an expensive problem. Protecting your options is the whole game.
Your Credit Profile Is Your Financial Reputation
The clearest way to understand credit scoring is as a reputation system. Lenders are not mainly asking whether you owe money today. They are asking how you have handled commitments over time, and they read the answer from your credit reports.
While scoring models differ, they consistently reward the same behaviours. Payment history — paying on time, every time — is the heaviest factor in common scoring models, alongside how much of your available revolving credit you are using. Around those sit the length of your credit history, the mix of credit types you manage, and how often you apply for new credit. The order matters more than the detail: habits beat gestures. One large payment does not outweigh a pattern of late ones, which is why steady, boring consistency is what builds a strong profile.
This framing changes the goal. Instead of asking “how do I avoid credit?”, ask “how do I demonstrate, month after month, that I use credit responsibly?” The payoff is concrete: better approval odds, lower interest rates, higher limits offered on better terms, and more room to manoeuvre when life changes direction.
It also makes one routine non-negotiable: check your credit reports regularly and dispute errors. Mistakes happen — wrong balances, accounts that are not yours, payments marked late that were not — and an error you never look for can cost you money for years. Consumer regulators encourage exactly this habit: review your reports, and get errors corrected, because the report is what lenders see when they price your reputation.
A Credit Limit Is Not Income
If the resource mindset has a safety catch, it is this sentence. Credit is borrowed capacity, not earnings. A lender sets a limit using broad rules about risk; it has no idea what your real monthly life can comfortably carry. Confusing the two — treating approval as affordability — is the single most common route from “credit as a resource” to credit as a crisis.
In practice, the healthiest credit use looks almost disappointingly dull. Purchases are planned rather than impulsive. Balances are paid in full where possible, and where not, they are paid down on a schedule the borrower chose, not one the minimum payment suggests. Due dates are automated so a busy week cannot cause a late mark. Available credit is treated as something to protect, because its protective value is the point.
A useful test before any credit purchase: would I buy this, at this total cost including interest, if I had to pay cash next month? If the honest answer is no, the resource is being consumed, not used.
Think in Terms of the Cost of Access
People who use credit well share a habit: they price decisions by their full cost of access, not by the sticker price. Every borrowing decision carries costs beyond the item itself — interest, fees, reduced borrowing capacity while the balance sits there, and possible score effects that make the next loan more expensive.
Utilization is where this becomes practical. Using a large share of your available revolving credit makes you look stretched to scoring models, even if you have never missed a payment. Many advisers suggest keeping usage well below your limits — below roughly a third is a common rule of thumb, and lower is generally better. The mechanics are simple: a balance that sits at ninety percent of a limit reads as pressure; the same balance at fifteen percent reads as control.
Run everyday choices through this lens and the maths changes. Carrying a balance for a non-essential purchase does not just cost the interest; it raises the price of your next borrowing too. Paying a card down does not just reduce debt; it restores capacity and improves the reputation that future lenders will price. That is the resource mindset doing arithmetic.
Six Habits That Keep Credit Working for You
Mindset becomes real through routine. These six habits are the operating system of everyone who treats credit as a resource.
- Automate on-time payments. Set up automatic payments for at least the minimum on every account, then pay extra manually when you can. This one system removes the most damaging and most avoidable mark on a credit file: the accidental late payment.
- Keep utilization low on purpose. Spread spending across cards if you have more than one, ask for limit increases on cards you manage well (without spending against them), and consider paying mid-cycle so reported balances stay low.
- Keep old accounts open. The age of your accounts supports your score, so closing your oldest card can shorten your history and raise your utilization at the same time. If an old card has no annual fee, keeping it open with occasional small use usually serves you better.
- Apply for credit sparingly and deliberately. Each application can leave an inquiry on your report, and a burst of applications reads as desperation. Borrow for a reason, on a schedule, not in a spree.
- Review your reports like a statement. Read them the way you would read a bank statement: regularly, and with a pen. Correct errors promptly and in writing where the bureau requires it.
- Keep credit in its place in the plan. Credit sits behind cash savings, not in front of them. An emergency fund handles the first shock; credit is the backup layer, there because the fund exists to repay it.
Using Credit for Growth, Not Just Emergencies
Credit is usually discussed only when something has gone wrong. Yet some of the best uses of a strong profile are offensive, in the planning sense: moves that improve your position rather than rescue it.
Refinancing expensive debt into a cheaper, simpler structure is the classic example — the same debt, carried at a lower cost, with one payment instead of four. Timing bridges are another: covering the gap between starting a better job and the first full salary, or funding a respected professional qualification — for instance, one of the leading business analyst certifications — whose return arrives over years. Building a record early is a third: a small, well-managed account in your twenties quietly becomes the long history your thirties will be grateful for.
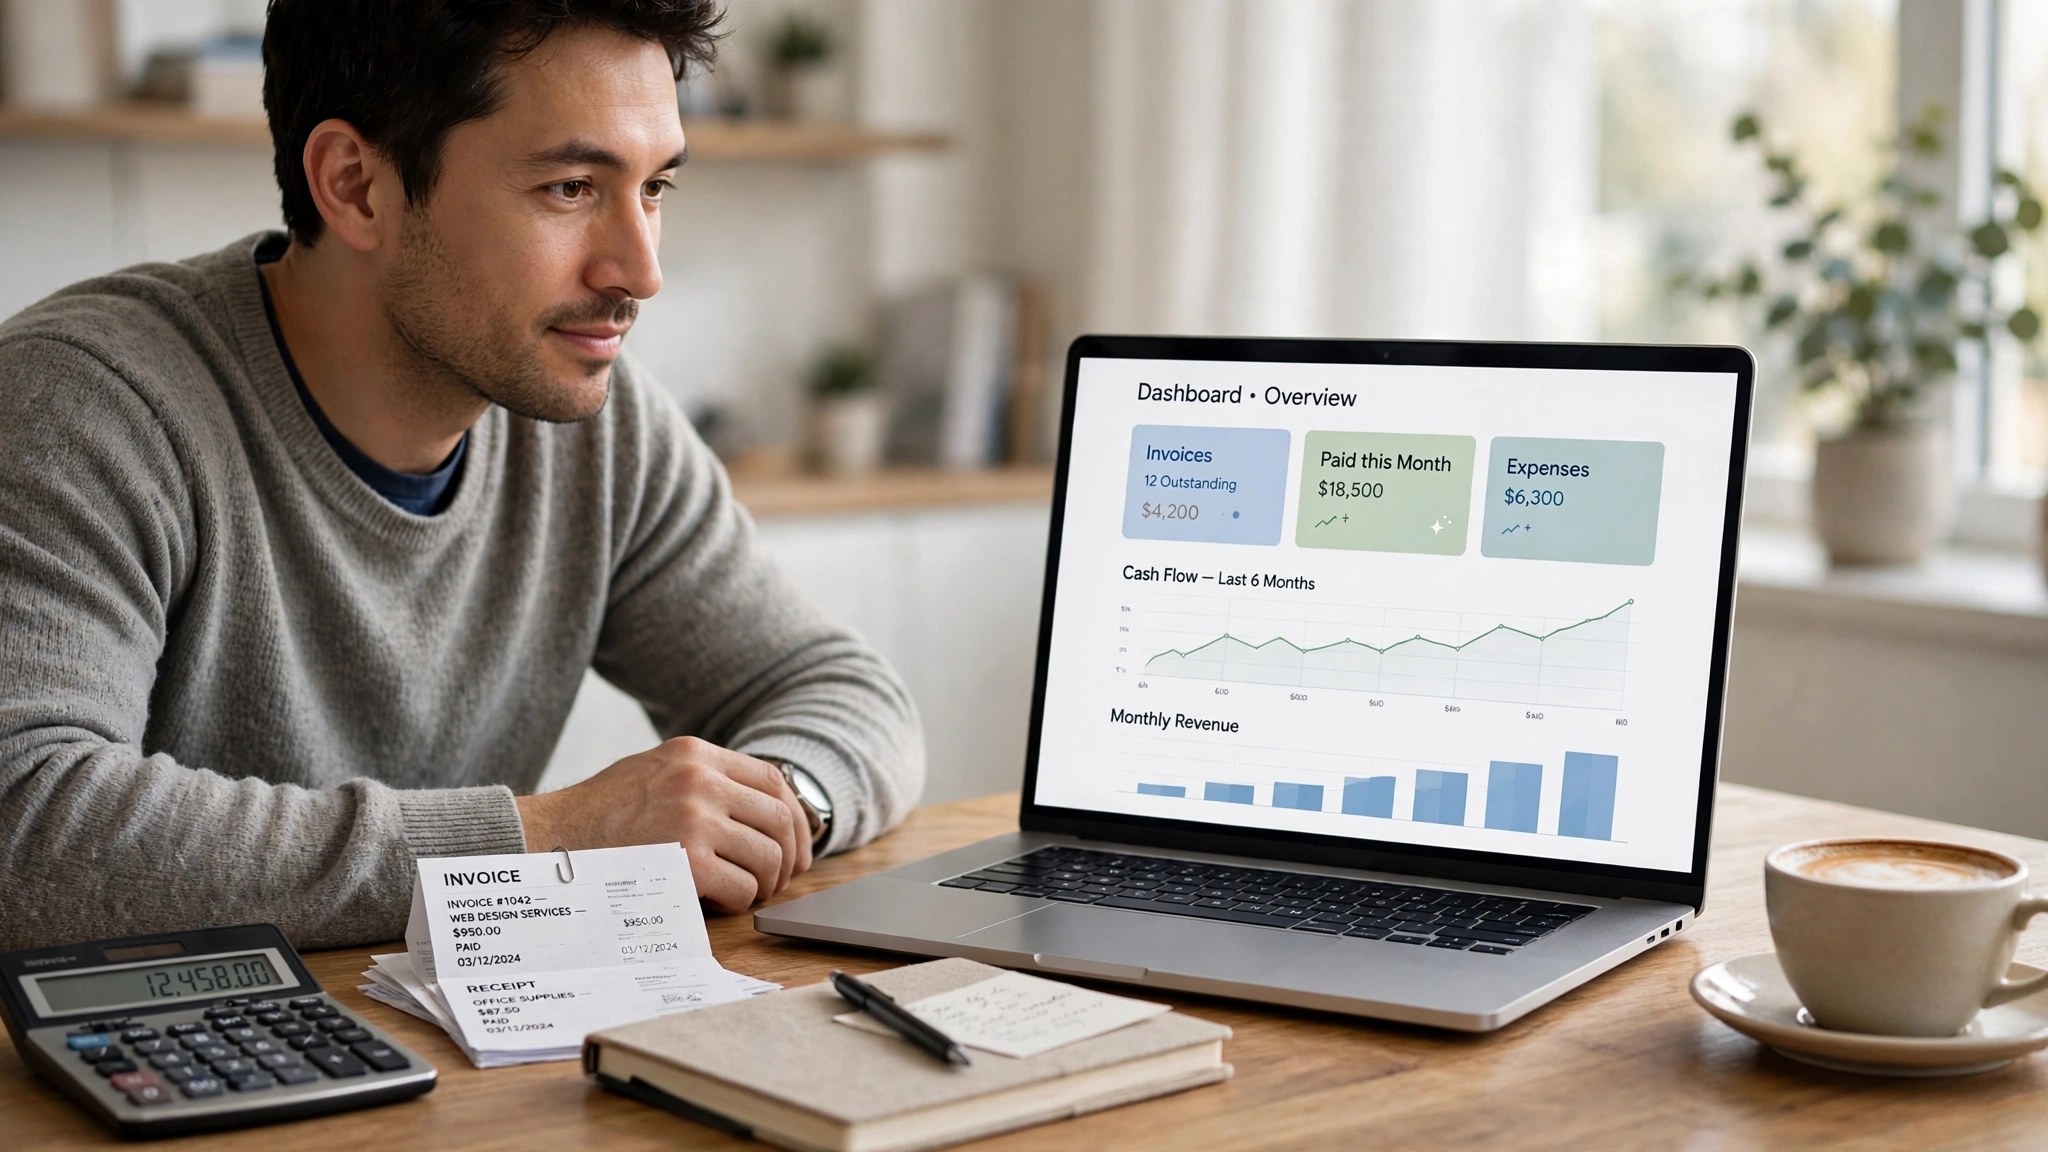
The same logic runs a business. A company with orderly books — the kind a good accounting platform makes almost automatic — can show lenders clean records, borrow at sensible rates, and time investments instead of begging for them. Owners who treat the company’s credit as part of their wider business strategy might, for example, use a credit line deliberately to fund business automation that cuts monthly costs — borrowing that pays for itself — rather than drifting into overdrafts that fund nothing.
The judging question never changes: does this borrowing protect income, remove more expensive debt, or build a better long-term position? If it mainly postpones discomfort, it fails the test, whatever the limit says.
What to Do If Credit Already Feels Heavy
None of this requires a clean starting point. If credit currently feels like pressure rather than possibility, the resource framework is not closed to you — it becomes a rebuilding plan.
Start with a complete, honest inventory: every balance, every interest rate, every minimum payment, every due date, in one list. Then separate emergencies from structure. A short-term cash crunch needs a short-term response; chronic overextension needs a structural one. From there, the usual tools apply in order of cost: tighten spending to free a real payment amount, call lenders to ask about hardship terms before you miss payments rather than after, and consider whether consolidating balances genuinely lowers your total cost or merely stretches it.
If the situation is bigger than self-management, that is precisely what reputable, non-profit credit counseling exists for: a structured review of your budget and debts, and where appropriate a managed repayment plan. Seeking that help early is not the opposite of the resource mindset; it is the mindset, applied honestly — recovering the function of credit instead of letting it drain you monthly.
Then rebuild the boring way: on-time payments without exception, one small account used lightly and paid in full, utilization falling month by month. Credit reputations are repaired the same way they were built, by pattern, and patterns need months, not weekends. Anyone who promises faster is selling something.
Common Credit Mistakes That Shrink Your Options
- Paying only the minimum. Minimum payments are designed to keep accounts current, not to clear them. Balances linger, interest compounds, and utilization stays high enough to keep your score — and your options — suppressed.
- Maxing out one card while others sit empty. Scoring models look at overall utilization and at individual cards. One card at its limit reads as strain even when the total picture is fine.
- Closing old cards after paying them off. It feels like progress, but it shortens your credit history and instantly raises your utilization on what remains. Paid-off and open is usually the stronger position.
- Ignoring your reports. Errors and even fraudulent accounts can sit unnoticed for years, quietly pricing you as a riskier borrower than you are.
- Borrowing to maintain appearances. Credit spent on signalling — the lifestyle purchase that impresses briefly — is the most expensive kind, because it converts your future flexibility into someone else’s opinion.
- Treating a limit increase as a raise. A higher limit improves your utilization maths only if your spending does not follow it up.
Final Thoughts
Reframing credit as a resource is ultimately about agency. It replaces two unhelpful stories — credit as a moral failing, or credit as a personality trait of the careless — with a plainer one: credit is a system that prices your reliability, and you can manage what it says about you.
The strongest financial position is rarely zero borrowing at all times. It is the combination of cash reserves, healthy credit access kept in good repair, low borrowing costs, and the awareness to know which tool a situation calls for. Credit works best when it is neither feared nor worshipped, only respected — maintained like the resource it is, and spent, when it is spent at all, on things that leave you stronger than before.
| 🔗 You may also like: |
|---|
| Business strategy: how to build a strong plan for long-term success |
| 5 Proven Business Analyst Certifications to Boost Your Career |
Frequently Asked Questions
Is it sensible to use credit when I could pay cash?
Sometimes, yes — with discipline. Using a card for planned purchases you could afford in cash, then paying the statement in full, builds the payment history and low-utilization pattern that keep your profile strong, at zero interest cost. The moment a balance starts rolling over for everyday spending, the logic reverses: pay cash and rebuild the habit.
What is credit utilization, and why does it matter so much?
Utilization is the share of your available revolving credit that you are using — a balance of 3,000 against limits totalling 10,000 is thirty percent. Scoring models treat high utilization as a sign of financial pressure, so it can pull a score down even with perfect payments. Keeping balances low relative to limits is one of the fastest legitimate ways to support a healthier profile.
Does checking my own credit report hurt my score?
No. Checking your own report is a soft inquiry and does not affect your score. Hard inquiries happen when a lender checks your report because you applied for credit, and those can cause a small, temporary dip. Reviewing your own reports regularly is encouraged — it is how errors and fraud get caught early.
How long does it take to rebuild a damaged credit profile?
There is no honest shortcut. Recent late payments fade in impact as a new pattern of on-time payments builds, and utilization improvements can show within a billing cycle or two once balances are reported lower. Serious rebuilding is measured in months to a few years depending on what happened, which is why starting now — with automated payments and falling balances — beats waiting for a better moment.
Can having a lot of available credit hurt me?
Available credit itself is not the problem; how it is used is what gets judged. High total limits with low balances generally support a score by keeping utilization low. The risks are behavioural — the temptation to spend up to the capacity — and practical, since some lenders look at total exposure when assessing large applications. If a limit tempts you, the answer is to manage the habit, not to shrink the resource.